
GP vs LP is the first decision you make in any apartment syndication, and most people make it without realizing it. I have owned and managed more than 2,000 properties, and I lost roughly $50 million in the 2008 crash, so I have sat in both seats and paid tuition in both. The seat you choose decides how much control you have, how you get paid, how many hours you work and how much risk you carry.
This guide breaks down the general partner and limited partner roles in plain language, shows you exactly how each one gets paid with real numbers, and gives you a simple framework for deciding which seat fits you right now.
In this guide:
- GP vs LP: The Short Answer
- The 5 C’s of GP vs LP
- What a General Partner Actually Does
- What a Limited Partner Gets and Gives Up
- How GPs and LPs Get Paid
- Liability, Taxes and SEC Rules
- GP vs LP Side by Side
- How to Vet a GP Before You Invest
- What the Best Syndicators Taught Me
- GP vs LP FAQ
- Ready to Take the Next Step?
GP vs LP: The Short Answer
In a real estate syndication, the general partner (GP) finds the deal, raises the money, signs the loan and runs the property. The limited partner (LP) supplies most of the equity, has no say in daily decisions and can lose no more than what they invested. GPs earn fees plus a share of profits. LPs earn a preferred return plus a split.
A syndication is simply a group of investors pooling money to buy a property none of them would buy alone. The legal wrapper is usually an LLC or a limited partnership. The GP is the sponsor, the operator, the person whose name is on the business plan. The LPs are the passive investors who write checks and receive distributions.
If you want the deeper background on the structure itself, read my complete guide to multifamily syndications. If you are specifically trying to understand the passive seat, my article on what a limited partner is goes deeper on that one role. This article is about the comparison, and about helping you choose.
Are You Built to Be a GP? A Quick Self Check
Answer these honestly before you decide which side of the table you belong on:
- Do you have 15 to 20 hours a week for the next several years to find, underwrite and manage deals?
- Do you have a network of people who already trust you with money, or the patience to build one?
- Would you be comfortable signing personal guarantees on a loan worth millions of dollars?
- Can you handle a phone call that says the boiler failed, occupancy dropped and investors want answers?
- Are you willing to invest in education, legal counsel and a team before you earn a dollar?
- Does the idea of being responsible for other people’s retirement money energize you or scare you?
- Do you have a high paying career you would rather keep growing while your money works for you?
If you said yes to most of the first six, you have the makings of a GP. If the last question described you best, the LP seat may be the smarter play right now. Neither answer is better. They are different jobs.
The 5 C’s of GP vs LP
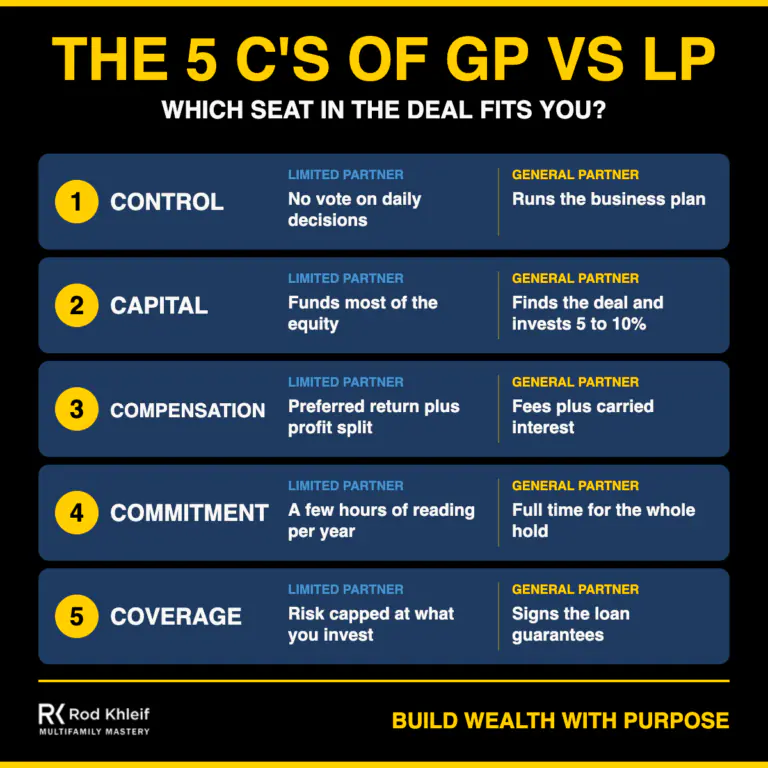
I teach students to compare the two seats using what I call the 5 C’s: Control, Capital, Compensation, Commitment and Coverage. Every difference between a GP and an LP fits into one of these five buckets, and once you see them side by side the decision gets much clearer. We work through this exact decision live at my multifamily bootcamp.
Want to work through the 5 C’s on a real deal with an experienced coach? Join the next Multifamily Bootcamp →
1. Control
The GP makes the decisions: which property to buy, which lender to use, which property manager to hire, when to raise rents, when to refinance and when to sell. LPs typically vote only on major events defined in the operating agreement, such as removing the GP for cause or approving a sale outside the business plan. If you need to be in the driver’s seat, you need to be a GP.
2. Capital
LPs usually provide 80 to 95 percent of the equity. GPs often invest 5 to 10 percent of the raise alongside their investors, and many experienced LPs insist on it because it means the sponsor loses money first if the deal goes sideways. The GP’s bigger contribution is the deal itself, the loan guarantee and years of work.
3. Compensation
The LP is paid first. In a typical deal, LPs receive a preferred return, commonly 6 to 8 percent per year, before the GP shares in any profit. After that, profits are split, often 70/30 or 80/20 in favor of the LPs. The GP earns fees for doing the work and a share of profits called carried interest or the promote. I break the math down below.
4. Commitment
An LP might spend a few hours vetting a sponsor and reading quarterly reports. A GP commits years of active work for the entire hold period, which is often five to seven years. You cannot quit halfway because your investors are counting on you.
5. Coverage
Coverage is about who is exposed when things go wrong. An LP’s downside is generally capped at what they invested. The GP typically signs the loan guarantees, including the so called bad boy carve outs that make them personally liable for fraud, misrepresentation or certain other acts, and carries the reputation risk if a deal fails.
What a General Partner Actually Does
When people picture a GP they picture the payday at sale. The real job looks like this:
- Finding the deal. Building broker relationships and underwriting dozens of properties to buy one.
- Underwriting. Projecting rents, expenses and net operating income, which is the income left after operating expenses and before debt payments. My free deal underwriting tool and cap rate calculator help here.
- Securing financing. Qualifying for and guaranteeing the loan, including bridge debt when a property needs heavy renovation. See my guide to multifamily bridge loans.
- Raising capital. Presenting the deal to investors legally and collecting commitments.
- Executing the business plan. Overseeing the property manager, renovations, leasing and expenses.
- Reporting. Sending monthly or quarterly updates, distributions and annual tax documents.
Most successful GPs do not do all of this alone. They form a GP team where one partner finds deals, one raises capital and one handles asset management. If you want to see how capital raisers fit into a team, read how to raise money for real estate deals.
What a Limited Partner Gets and Gives Up
As an LP you get access to large apartment communities, professional management, monthly or quarterly cash flow, depreciation benefits and a share of the profit at sale, all without fixing a single toilet. That is a powerful trade for a doctor, an executive or a business owner who has more money than time.
Here is what you give up:
- Control. You cannot fire the property manager or decide when to sell.
- Liquidity. Your money is typically locked up until a refinance or sale, often five years or more.
- A share of the upside. The GP earns fees and a promote for doing the work.
- Information. You see what the sponsor reports. That is why vetting the GP matters more than vetting the property.
The single biggest predictor of how an LP investment turns out is the quality and integrity of the GP. I cover how to evaluate one step by step later in this article.
How GPs and LPs Get Paid: Fees, Pref and Splits
The order in which money flows is called the distribution waterfall. The details live in the operating agreement, but most deals look something like this:
- Preferred return to LPs. LPs receive their pref, for example 8 percent per year, before the GP receives any profit share.
- Return of capital. At refinance or sale, LPs get their original investment back.
- Profit split. Remaining profit is divided, for example 70 percent to LPs and 30 percent to the GP.
Separately, the GP usually earns some combination of these fees, which you should always find disclosed in the offering documents:
- Acquisition fee: commonly 1 to 3 percent of the purchase price, paid at closing.
- Asset management fee: commonly 1 to 2 percent of collected revenue or equity per year.
- Refinance or disposition fee: sometimes charged at a capital event.
Some deals add a catch up provision or tiered splits that increase the GP share after LPs hit a certain return. For a full worked example with a catch up, read my article on the syndication waterfall.
Three Worked LP Scenarios
Let me make this real. Imagine a hypothetical deal that raises $5,000,000 from LPs, pays an 8 percent preferred return every year from cash flow, holds for five years, and sells with $8,000,000 left for the equity investors after the loan is repaid. LPs first get their $5,000,000 back. The remaining $3,000,000 is split 70/30, so LPs share $2,100,000 and the GP earns $900,000 of carried interest.

Every LP in this example earns the same 1.82x equity multiple, meaning $1.82 back for every dollar invested, no matter how big the check. What changes is the dollar amount. A $50,000 investor receives $91,000 in total. A $100,000 investor receives $182,000. A $250,000 investor receives $455,000. Meanwhile the GP earned $900,000 for finding, financing and running the deal, plus fees. That is the trade: the LP gets priority and safety, and the GP gets leverage on their time and expertise.
Remember this is a simplified illustration. Real deals have expenses, timing differences, possible capital calls and no guaranteed outcome. Always read the actual private placement memorandum.
Liability, Taxes and SEC Rules for GP vs LP
This is where many online articles get it wrong, so let me be precise. You should always confirm specifics with your own attorney and CPA.
Liability
Most modern syndications are structured as LLCs, and the GP usually acts through its own management LLC. That entity structure limits liability for both sides in ordinary business losses. The real personal exposure for a GP comes from the loan: many lenders require the sponsor to sign a personal guarantee or carve out guarantee, and the GP carries fiduciary duties to investors. LPs generally risk only the capital they put in.
Taxes
Both GPs and LPs receive a Schedule K-1 each year reporting their share of income, losses and depreciation. You can read the IRS description of the Schedule K-1 for partnerships. Depreciation often offsets much of the cash flow on paper, which is one reason high income professionals like the LP seat. Whether passive losses can offset your other income depends on your situation, so talk to a tax professional.
SEC Rules
Selling LP interests is selling a security, so GPs must follow federal securities law. Most syndications use Regulation D, Rule 506, and I compare the two versions in detail in my article on 506(b) vs 506(c) syndications. Under Rule 506, a 506(b) offering cannot be publicly advertised but can accept up to 35 sophisticated investors who are not accredited, while a 506(c) offering can be advertised but every investor must be accredited and the sponsor must take reasonable steps to verify it. In March 2025, SEC staff guidance indicated that high minimum investment amounts can be one of those reasonable steps.
The accredited investor definition in Rule 501 includes individuals with income over $200,000, or $300,000 together with a spouse or spousal equivalent, in each of the last two years with the same expected this year, or a net worth over $1,000,000 excluding a primary residence. Certain licensed professionals also qualify. My podcast conversation with SEC syndication attorney Mauricio Rauld goes deep on staying compliant as a GP.
If you want the fundamentals of how GPs and LPs fit into a lifetime cash flow plan, my book is the best place to start. It walks through how I built and rebuilt my portfolio, and it is free. Click the cover below to get your copy.
GP vs LP Side by Side
Here is the whole comparison in one place.
How to Vet a GP Before You Invest as an LP
If you choose the LP seat, your most important job is choosing the right GP. Here is the process I recommend.
- Check the track record. Ask for every deal the sponsor has completed, including the ones that underperformed, with projected versus actual returns.
- Confirm the GP invests alongside you. Ask how much of their own money is in the deal.
- Stress test the underwriting. Look at the rent growth, exit cap rate and occupancy assumptions. Conservative numbers beat exciting numbers.
- Read the fee schedule and waterfall. Every fee and split should be clearly disclosed in the private placement memorandum and operating agreement.
- Review the debt. Understand the loan type, rate, term and any interest rate cap. Short term floating debt hurt many sponsors in recent years.
- Call past investors. Ask how the GP communicated when things went wrong, not just when they went right.
For a broader checklist on the property itself, see my multifamily due diligence guide.
What the Best Syndicators Taught Me About This
I have interviewed hundreds of investors on the Lifetime Cash Flow podcast, and the GP vs LP question comes up constantly. In my conversation with Michael Blank on raising capital at scale, we talked about how GPs earn investor trust long before they ever ask for a check.
Watch the Full Interview
Michael Blank walks through how general partners raise capital at scale and build trust with limited partners.
Matt Faircloth, author of a well known book on raising private capital, explained in our episode on raising private capital why the GP’s job is really a relationship business. And Hunter Thompson shared how he thinks about serving passive investors as a capital raiser. The common thread is simple: great GPs treat LP money with more care than their own.
Rod Khleif: “Your first job as a general partner is not finding a deal. It is protecting the people who trusted you with their money. Get that right and the deals, the capital and the wealth will follow.”
Many of my students start as LPs to learn how deals work from the inside, then move into the GP seat once they have the knowledge, the team and the confidence. When they are ready to scale, that is what our syndication coaching for professional investors is built for.
GP vs LP FAQ
Q: What is the difference between a GP and an LP in real estate?
A: The general partner finds, finances and manages the property and makes all operating decisions. The limited partner invests capital passively, has no role in daily management and generally risks only what they invested.
Q: Who gets paid first, the GP or the LP?
A: In most syndications the LPs get paid first through a preferred return and the return of their capital. The GP shares in profits only after those hurdles are met, although the GP may earn disclosed fees along the way.
Q: What is a typical GP and LP split?
A: Common splits are 70/30 or 80/20 in favor of the LPs after the preferred return. Some deals use tiered splits that give the GP a larger share once LPs reach higher return levels.
Q: What is a preferred return?
A: A preferred return is the annual return LPs receive before the GP shares in profits, commonly 6 to 8 percent. It is a priority of payment, not a guarantee, so if the property does not produce enough cash it may accrue or go unpaid.
Q: What is carried interest in real estate?
A: Carried interest, also called the promote, is the GP’s share of profits above the preferred return and return of capital. It rewards the GP for creating value and aligns them with investor results.
Q: Do GPs have unlimited liability?
A: In a traditional limited partnership the general partner can have unlimited liability, but most modern syndications use LLCs that limit liability for ordinary business debts. GPs still take on personal risk through loan guarantees and fiduciary duties to investors.
Q: Do I need to be accredited to be an LP?
A: It depends on the offering. A 506(c) offering requires every investor to be accredited, while a 506(b) offering can accept up to 35 sophisticated investors who are not accredited, provided the sponsor has a preexisting relationship with them.
Q: How much does it cost to invest as an LP?
A: Minimum investments commonly range from $25,000 to $100,000 per deal, and some sponsors set higher minimums. The offering documents state the exact minimum.
Q: Can I be both a GP and an LP?
A: Yes. Many sponsors invest as LPs in their own deals so their money sits alongside investors, and many active GPs invest passively in other sponsors’ deals to diversify.
Q: Should I start as a GP or an LP?
A: If you have more capital than time, start as an LP and learn from great sponsors. If you have time, drive and a willingness to build a network and a team, get educated and start building toward the GP seat.
Ready to Take the Next Step?
Whether you end up as a GP, an LP or both, the fastest path is learning from people who have done it. At my bootcamp you will see real deals, real waterfalls and real GP teams, and you will leave knowing which seat fits you.
Reserve your seat at the Multifamily Bootcamp →
Not ready for a bootcamp yet? Start with my free book and learn the fundamentals at your own pace.
Download your free copy of How to Create Lifetime Cashflow Through Multifamily Properties →
Disclaimer: This article was written with the help of AI and reviewed by Rod and his team. It is for educational purposes only and is not legal, tax or investment advice.
